Market Overview: Defining the Scope of the Religious And Spiritual Products Market
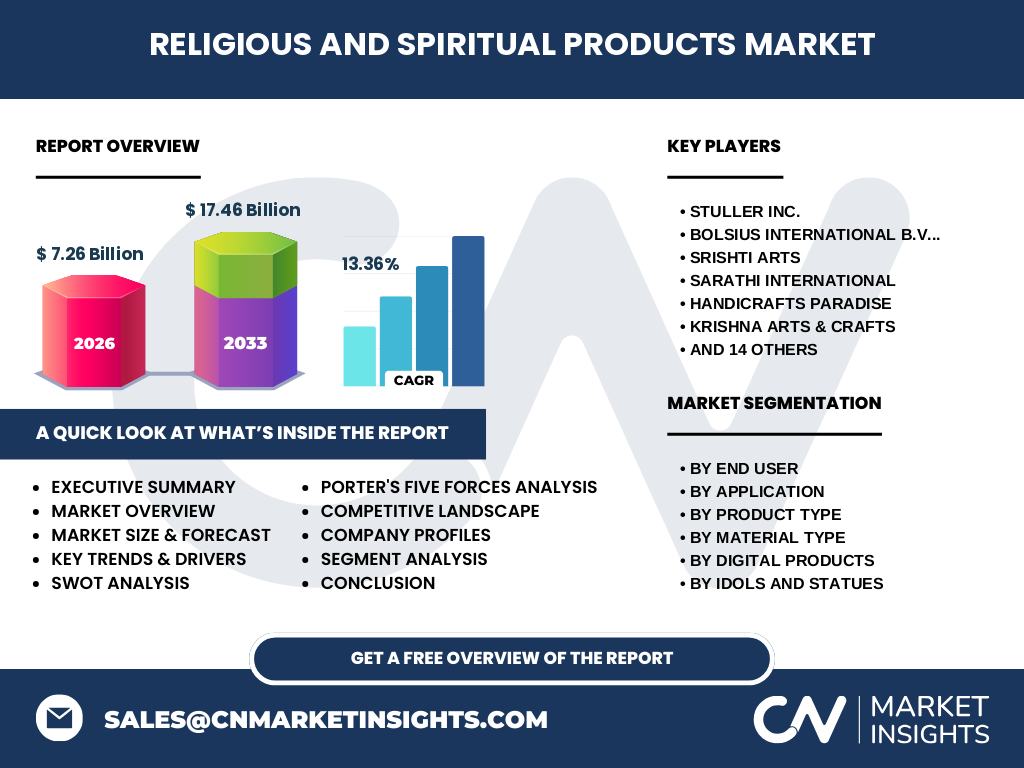
Our proprietary research values the Religious And Spiritual Products Market at 7.26 Billion in 2026, encompassing a diverse ecosystem of physical artifacts and digital solutions. This sector services individual consumers, religious institutions, spiritual centers, and cultural organizations, operating through specialized retail, online channels, and global logistics hubs moving goods from raw materials to end-users.
Structural Growth Drivers and Market Restraints
The market is propelled by a CAGR of 13.36%, driven by surging demand for mental wellness tools and heritage preservation. However, supply chain vulnerabilities involving raw materials like precious metals and exotic woods, coupled with strict regional import regulations on sacred items, act as notable restraints for growing enterprises.
Emerging Trends Reshaping Industry Patterns
A defining shift in the Religious And Spiritual Products Market industry trends is the integration of technology, highlighted by AI-powered spiritual tools, mobile apps, and digital worship platforms. Concurrently, eco-conscious consumers are fueling demand for sustainable items like seed-based prayer beads and beeswax candles.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic drastically accelerated the digital transformation of the Religious And Spiritual Products Market analysis, as physical temples and specialty stores faced closures. This catalyzed rapid adoption of online retail channels, software for institutions, and digital content, securing a robust post-pandemic recovery trajectory.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately fragmented, featuring key innovators like Stuller Inc. and Bolsius International B.V. alongside traditional artisans. Strategic dynamics involve scaling direct-to-consumer e-commerce, expanding sustainable product portfolios, and partnering with eco-initiatives like HelpUsGreen to capture conscious consumers.
Executive Summary of Key Industry Findings
Our analysis indicates that the Religious And Spiritual Products Market market size is poised for explosive expansion, scaling from 7.26 Billion in 2026 to 17.46 Billion by 2033. Success in this landscape heavily favors agile enterprises merging traditional craftsmanship with modern digital distribution platforms.
Long-Term Market Forecast from 2027 to 2033
Based on our research, the sector will maintain a strong 13.36% CAGR throughout the forecast period, culminating in a market valuation of 17.46 Billion by 2033. This sustained momentum is underpinned by rising disposable incomes and a global renaissance in personal devotion and mindfulness practices.
Comprehensive Segmentation Analysis
The market segments by end-user, application, product type, material, and distribution channel. Key product categories range from Idols And Statues and Incense And Candles to Digital Products and Religious Jewelry And Symbols, each serving distinct ritualistic, domestic, and institutional use cases worldwide.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with Asia-Pacific dominating production of metal deity idols and wooden carved statues, while North America and Europe represent primary consumption hubs for crystal prayer beads, scented devotional candles, and online spiritual services.
In-Depth Regional Review and Localized Constraints
Localized market constraints involve strict customs compliance regarding sacred animal products and precious stones. Ports in South Asia and Europe serve as critical logistical bottlenecks and gateways for exporting fragile handicrafts, incense sticks, and sacred books globally.
Strategic Positioning of Leading Company Profiles
Industry leaders occupy distinct niches; for instance, Bolsius International B.V. dominates ritual candle manufacturing, while Rudra Centre Services Pvt. Ltd. specializes in authentic prayer beads and spiritual counseling. Meanwhile, innovators like HelpUsGreen pioneer floral recycling into incense.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers is moderate due to abundant artisan alternatives, whereas supplier power for raw materials like genuine sandalwood and gemstones remains high. Threat of substitution is low for core faith items but moderate for generic home decor.
SWOT Analysis of the Sector
Strengths include deep cultural roots and high consumer loyalty. Weaknesses involve supply chain fragmentation. Opportunities lie in AI-powered spiritual tools and global e-commerce expansion. Threats feature counterfeit religious artifacts and stringent international trade regulations.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw material extraction—such as timber, clay, and precious metals—through artisan manufacturing and rigorous quality control by firms like Handicrafts Paradise, culminating in omnichannel distribution via specialty stores and online retail.
High-Potential Investment Insights and Recommendations
Investors should target high-growth niches such as digital worship software, AI-powered spiritual tools, and certified eco-friendly incense. Companies with robust direct-to-consumer digital infrastructure offer superior risk-adjusted returns within this expanding market.
Conclusion and Strategic Takeaways
The Religious And Spiritual Products Market offers compelling commercial prospects, driven by a powerful 13.36% CAGR. Stakeholders must embrace digital transformation and sustainable sourcing to maintain competitive advantage through 2033.
Robust Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by cross-referencing trade registry data, primary stakeholder interviews with executives from firms like Sarathi International, and secondary macroeconomic indicators regarding global wellness spending and e-commerce penetration rates.
Scope of the Report and Coverage Parameters
This report evaluates the global market across specified product lines, material types, and digital offerings from 2026 to 2033. Limitations include restricted data transparency in informal artisan economies across emerging rural markets.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features key players launching eco-friendly product lines, securing strategic logistics partnerships to ease cross-border shipping, and rolling out advanced mobile apps for digital worship, reflecting an industry-wide pivot toward tech-enabled spirituality.